Your credit report should tell the truth. We make sure it does.
Errors, outdated accounts and items that can't be verified can drag your score down and cost you thousands in interest. Credit 4 Days finds them, disputes them with the bureaus, and keeps you posted every step of the way.
Hear from us before you get started.
A one-minute message from the Credit 4 Days team.
Making sure what's on your credit report is accurate, complete and provable.
Your credit score comes from your reports at Equifax, Experian and TransUnion. Lenders, landlords and insurers rely on them. Federal law, the Fair Credit Reporting Act (FCRA), says those reports have to be accurate, and it gives you the right to challenge anything that isn't.
We review all three reports
We go through your Equifax, Experian and TransUnion reports line by line. We look for wrong balances, late payments that weren't late, duplicate collections, accounts that aren't yours, and old items that should have dropped off.
We dispute with the bureaus
We prepare and send detailed disputes, backed by your rights under the FCRA, to each bureau and, when needed, directly to the creditor that reported the item.
You watch your profile improve
When an item can't be verified, it has to be corrected or deleted. We track every response, follow up, and show you what changed.
That's what credit repair is for. It isn't a trick or a loophole. It's using the dispute rights the law already gives you, done carefully and followed up on until there's an answer.
A better score can mean a lower interest rate, and that adds up to real money.
Lenders price loans by risk. The higher your score, the lower the rate they usually offer. Here's what different rates do to the same $300,000, 30-year mortgage.
Total interest paid over 30 years on a $300,000 loan, principal and interest only.
less interest at 6.5% than at 8.5%. That's about $411 a month back in your pocket.
On a car loan, the lower rate saves about $6,240 in interest.
These are example rates to show how the math works, not quotes or a promise of a specific rate. Real rates depend on the lender, the market, your income, your down payment and your full credit profile. To see today's rates by score range, use the myFICO Loan Savings Calculator.2
A clear, legal process with four steps.
Under the FCRA, when you dispute an item the credit bureau generally has 30 days to investigate. If the information can't be verified as accurate, it has to be corrected or removed.3
Intake
You fill out our short form and connect your credit monitoring so we can pull all three reports.
Audit
We flag every item that's inaccurate, incomplete, outdated or unverifiable, and walk you through what we found.
Dispute
We send targeted disputes to the bureaus and, where it helps, to the original creditors and collectors.
Track & repeat
We log every result, escalate items that come back "verified" without proof, and keep you updated.
This is an illustrated example, not a real client file. Every report is different, and results depend on what's on yours.
What the process looks like on real reports.
These are screenshots from Credit 4 Days clients' credit monitoring dashboards, taken after a round of disputes. Names, account numbers and addresses have been removed.
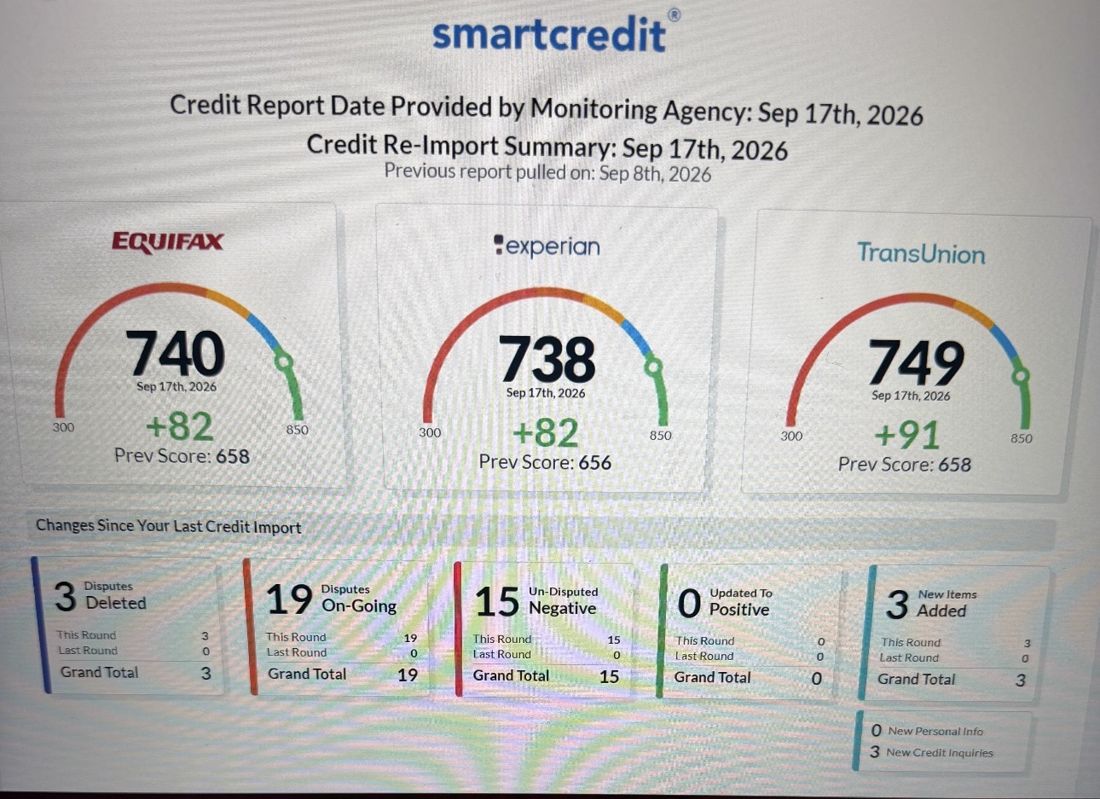
3 disputed items deleted this round, with 19 more still in progress.
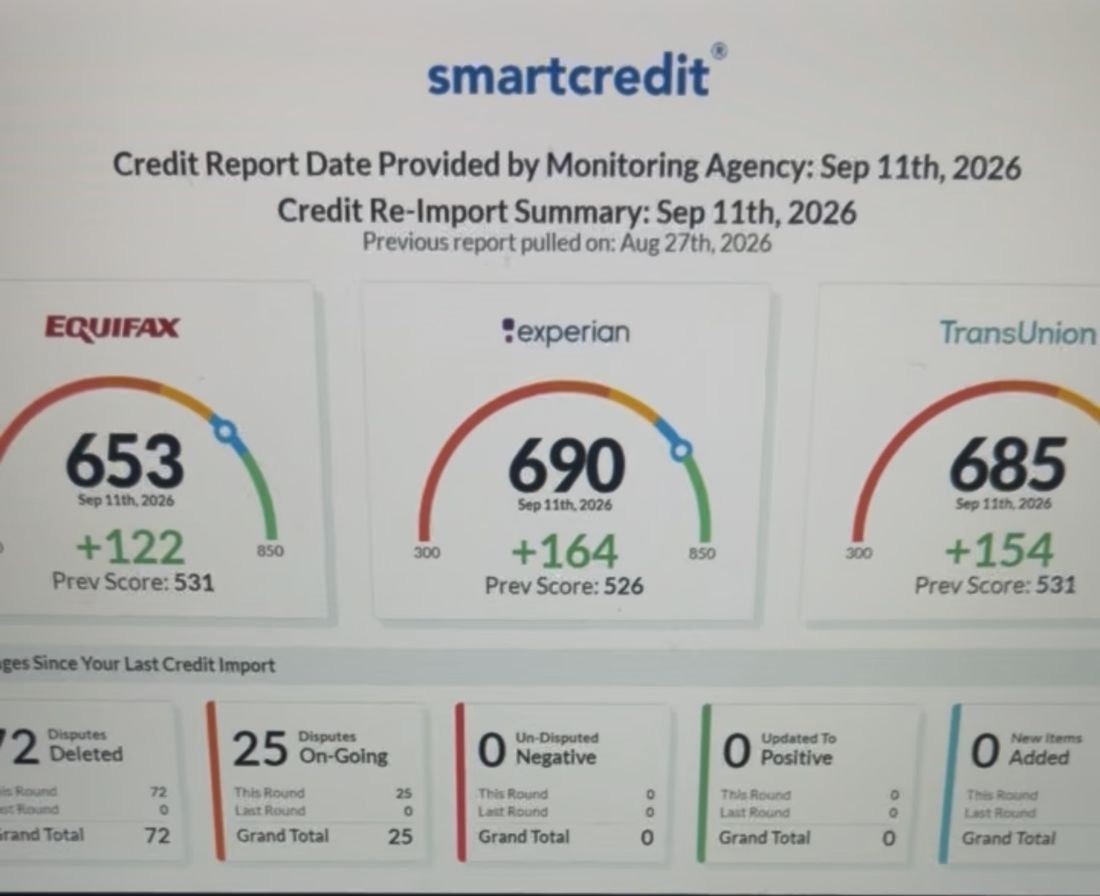
72 disputed items deleted in a single round.
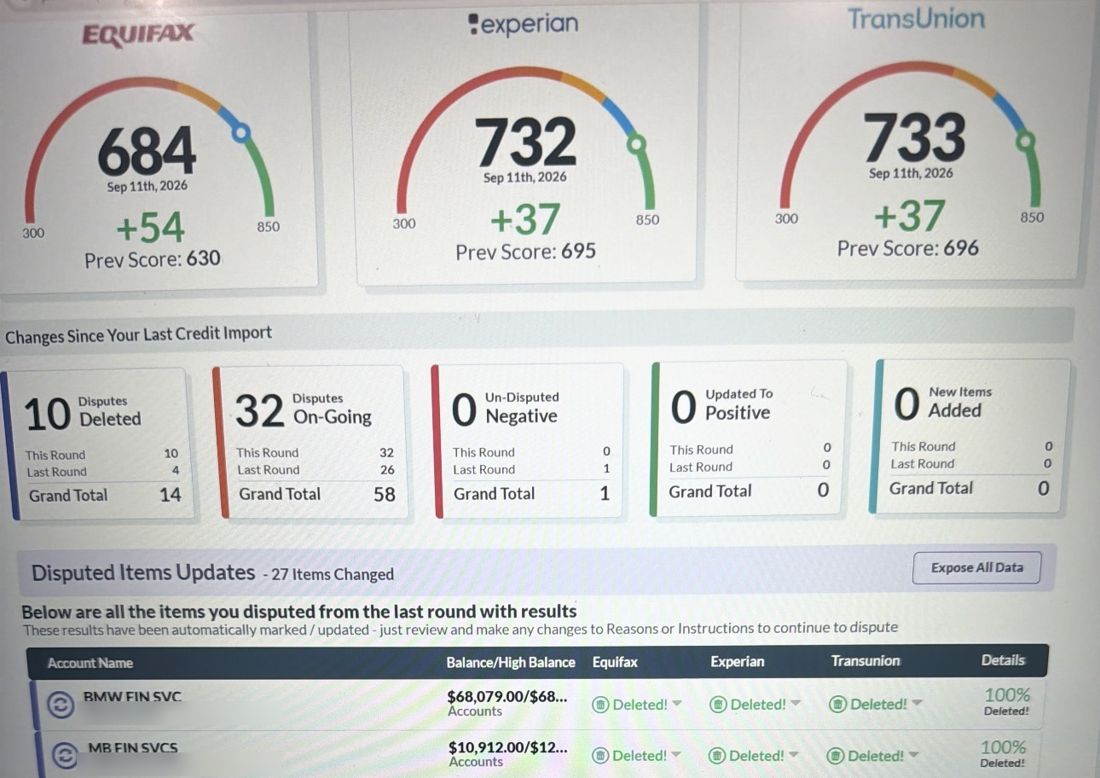
10 items deleted this round, including two auto finance accounts removed at all three bureaus.
Shared with each client's permission. These are individual results, not typical or guaranteed outcomes. Every credit file is different, and score changes can also reflect other things, like paying down balances. Click any screenshot to see it full size.
What credit repair can and can't do.
What we do
- Challenge items that are inaccurate, incomplete, outdated or can't be verified
- Handle the letters, deadlines and follow-ups for you
- Explain every result and what to do next to build positive credit
What no one can honestly promise
- To remove accurate, current negative information. The law lets it stay for up to 7 years, and most bankruptcies for up to 10.4
- A specific score or a guaranteed timeline
- A "new identity" or a way around the credit system
You have the right to dispute errors on your own credit report directly with the bureaus at no cost. A credit repair company can't charge you before the services are fully performed, must give you a written contract, and must let you cancel within 3 business days.5
Let's find out what's holding your score back.
Fill out our short intake form. It takes about three minutes, and our team handles the heavy lifting from there.
Start my credit review- Federal Trade Commission, "In FTC Study, Five Percent of Consumers Had Errors on Their Credit Reports That Could Result in Less Favorable Terms for Loans" (Feb. 11, 2013). ftc.gov
- myFICO, Loan Savings Calculator. Current average rates by FICO score range. myfico.com. Example payments on this page were calculated with standard amortization math.
- Consumer Financial Protection Bureau, "How do I dispute an error on my credit report?" consumerfinance.gov; Fair Credit Reporting Act, 15 U.S.C. § 1681i.
- Fair Credit Reporting Act, 15 U.S.C. § 1681c (requirements relating to information contained in consumer reports).
- Credit Repair Organizations Act, 15 U.S.C. §§ 1679–1679j. govinfo.gov
Credit 4 Days is not a law firm and does not provide legal advice. We can't remove accurate, timely and verifiable information from your credit report. Results vary and are not guaranteed. Illustrations and examples on this page are for education only.